Did You Take Your 2020 RMD Too Soon?

As part of the CARES Act, the requirement for older taxpayers to take required minimum distributions (RMDs) from their retirement plans has been waived for 2020. This is primarily due to the drop in value for most investments as a result of the economic effects of COVID-19.

RMDs are required distributions from qualified retirement plans and are commonly associated with traditional IRAs, but they also apply to 401(k)s and SEP IRAs. The tax code does not allow taxpayers to indefinitely keep funds in their qualified retirement plans. Eventually, these assets must be distributed, and taxes must be paid on those distributions. If a retirement plan owner takes no distributions, or if the distributions are not large enough, then he or she may have to pay a 50% penalty on the amount that is not distributed.

RMDs historically have needed to begin in the year when the retirement plan owner became age 70½, but a late 2019 tax law change (the SECURE Act) upped the starting age to 72 for years after 2019. The first year’s distribution can be delayed to no later than April 1 of the subsequent year. However, delaying the first distribution means taking two distributions in the subsequent year.

The CARES Act RMD waiver applies to:
• The 2020 RMD for taxpayers who turned 70½ before 2020.
• The 2019 RMD for taxpayers who turned 70½ in 2019 and chose to defer their first distribution to 2020.
• The 2020 RMD for taxpayers who turned 72 in 2020.
• The RMDs for beneficiaries.

RMD Rollover: The 2020 waiver for RMDs was not announced until the CARES Act was passed on March 27, 2020. Normally, an RMD cannot be rolled over, but the CARES Act essentially changed 2020 RMDs into eligible rollover distributions, which can be rolled over within 60 days of being received. Some individuals subject to the RMD requirements had already taken their RMD before the CARES Act was enacted and did not have the opportunity to roll the RMD back into their retirement account if the 60-day rollover period had already expired.

That issue was alleviated by the declared disaster provisions extending the rollover period. Thus, any 60-day rollover period that ends on or after April 1, 2020, and before July 15, 2020, is extended through July 15, 2020. This means that if you took a distribution after the end of January, you can roll it back into the retirement plan and avoid being taxed on it in 2020, if you do so by July 15, 2020.

Be aware, however, that any part of the distribution from a traditional IRA or qualified retirement plan that you don’t roll over will be taxed. This means that if federal and/or state income tax was withheld from the distribution and you want to roll over the distribution, you will need to use funds other than those from the distribution in order to fully roll it over. Regrettably, the withholding can’t be refunded when you make the rollover. Instead, the withheld tax will be claimed as a credit on your 2020 return. In this case, your 2020 estimated tax installments and/or withholding on other income can be adjusted.

One other caveat: only one IRA-to-IRA rollover is allowed within any 12-month period, so if you have already made an IRA rollover – even for a different account – during the prior 12 months, then you will need to carefully time the IRA RMD rollover so that it occurs beyond that period but is still within the extended time limit. Trustee-to-trustee transfers don’t count as rollovers, so, for example, if you moved your IRA from one brokerage to another by having the account directly transferred, that action won’t count as a rollover.

Unfortunately, those who took their RMD in January do not benefit from the extension to July 15, 2020 (unless the IRS provides additional relief).

And, unless further relief is provided, the RMD requirements will resume in 2021. If you have questions or wonder what the pros and cons are related to a rollover, please give our office a call.
Achieving PPP Loan Forgiveness

Businesses that have managed to secure financing through the Paycheck Protection Program (PPP) are fortunate, but still face deciphering the ambiguous definitions and requirements for determining loan forgiveness. Owners and managers must carefully adhere to the terms of the program in order to qualify for loan forgiveness.
In response to the coronavirus pandemic, Congress created the Coronavirus Aid, Relief, and Economic Security (CARES) Act. The historic $2.2 trillion stimulus bills included $350 billion towards the PPP, a forgivable loan program to aid small businesses dealing with the financial impact resulting from the coronavirus pandemic. Unfortunately, the Small Business Administration (SBA) loan program was rapidly flooded with applications and the monies appropriated for relief and emergency loans were quickly extinguished. Congress has approved and President Trump signed on April 24 the additional $320 billion for the program.
While business owners who did secure a PPP loan are fortunate, they have a lot of work ahead of them. In order to qualify for loan forgiveness, the PPP funds must be used for certain allowable purposes, including:
  • Salaries, wages, commissions, or similar compensations (up to $100,000 per year per employee, prorated) should make up 75% of the money used;
  • Cash tips or equivalent;
  • Employee leave, including parental, family, medical, or sick (excluding family or sick leave under the Families First Coronavirus Response Act);
  • Allowances for dismissal or separation;
  • Group healthcare benefits, including insurance premiums;
  • Retirement benefits;
  • State or local taxes on employee compensation (not including the employer’s share of FICA payroll taxes, Railroad Retirement Act taxes, or other required U.S. income tax withholdings);
  • Continuation of group healthcare benefits during employee leave and insurance premiums;
  • Rent and utility payments;
  • Mortgage interest and interest on other debt obligations incurred prior to February 15, 2020;
  • Compensation and income of up to $100,000 per year (prorated) for sole proprietors and independent contractors.
Money used for any of the allowable purposes listed above will qualify for 100% forgiveness; loan money used for non-allowable purposes must be repaid. This means that businesses who take on PPP loans must shoulder the burden of new reporting requirements. Failure to keep thorough records of how the loan money is used could result in loss of forgiveness for some portions of the loan money. For detailed information specific to loan forgiveness, click here.
In order to qualify for loan forgiveness, recipients will need to provide banks with specific information, including up-to-date financials. Organizations should work closely with their financial team to better position themselves to comply with reporting regulations. Businesses without an internal team member would benefit greatly from securing outside help to adhere to the strict rules.
If your organization does not have the internal resources to prepare, or would just like help handling this task, consider reaching out to us at Slattery & Holman to discuss your options. Our team is prepared to help guide your organization in achieving successful PPP loan forgiveness and more. We can assist you with:
  • Bookkeeping catchup and cleanup for the first quarter of 2020
  • Preparation of payroll cost calculations needed for the PPP application
  • Assistance with PPP and other loan applications related to the coronavirus pandemic
  • Help with performing real-time reporting in order to adhere to loan forgiveness regulations
  • Advice and guidance for post-pandemic success
Our team is here to offer sound advice, clear guidance, and knowledgeable input to help you achieve financial relief during this uncertain time. Contact us today to discuss how we can accommodate your unique situation.

Where’s My Recovery Rebate?

To Our Clients and Friends,

As part of the recently enacted Coronavirus Aid, Relief, and Economic Security (CARES) Act, direct economic recovery payments are being distributed to eligible American taxpayers.

Distribution of recovery rebates began this week.

If you are expecting a federal recovery rebate, but have not yet received it, visit the IRS website for more information. The IRS recently released a tool to provide information about:

  • Your payment status
  • Your payment type
  • Whether the IRS needs more information from you, including bank account information

In order to access information about the status of your recovery rebate, you will be asked to supply the following information:

  • Your Social Security Number or Individual Tax ID Number
  • Your date of birth
  • Your street address and ZIP or postal code

Please note: you may be asked for specific information from your 2018 or 2019 tax return (if you have filed). We recommend having your tax return(s) on hand in case more information is needed.

Having trouble receiving your recovery rebate? You may have one of the following issues:

  1. Are you eligible for a recovery rebate? To receive any portion of the recovery rebate, you must fit all of the following three criteria: (1) be either a U.S. resident or citizen, (2) not be the dependent of another taxpayer, and (3) have a work-eligible Social Security Number. Additionally, there is an income limit set for receiving the rebate. You can read more here.
  2. Is your bank/mailing address up to date? The IRS will use the direct deposit information you supplied on your most recent tax return (either 2018 or 2019) to send your recovery rebate. If you received your last tax refund via a physical check, your rebate will be mailed to the residence you listed on your most recent tax return (either 2018 or 2019). For more information on how to update either of those items, please click here.
  3. Did you file a tax return? If you did not file a tax return in the last two years (2018 and/or 2019), the IRS needs more information from you. For guidance on how to submit the information required, review the information for non-filers by clicking here.

For more specific information on the recovery rebate, including in-depth information regarding eligibility, please visit our CARES Act FAQ blog.

Warm regards,

Slattery & Holman, P.C.

Watch Out for Coronavirus-Related Scams

On Thursday, April 2, the Internal Revenue Service (IRS) issued a warning concerning the development of new scams related to the coronavirus, particularly the recovery rebates legislated by the CARES Act. It is not surprising that criminals are taking advantage of the chaos resulting from the coronavirus outbreak to perpetrate fraud.

The IRS has observed an uptick in fraudulent requests related to the coronavirus outbreak. In particular, the economic impact payments legislated in the CARES Act have opened the door to new scams.

As a reminder, here are some facts about the economic impact payments:

  • The IRS exclusively uses the terminology “economic impact payment” to refer to the payment.
  • Most taxpayers will receive their economic impact payments via direct deposit into the bank account they previously provided on a 2018 or 2019 tax return.
  • Taxpayers without direct deposit information on file with the IRS will have the opportunity to provide banking information via a secure portal website. The website is still in development and does not yet exist.
  • Taxpayers for whom the IRS does not have or receive direct deposit information will be mailed a check to their address on file.
  • Retirees who do not normally file a tax return do not need to do anything. The IRS will use the information on file to automatically distribute economic impact payments to them.
  • Click here to learn more about economic impact payments. 

The IRS recommends that taxpayers watch out for emails, text messages, phone calls, websites, and social media requests containing any of the following:

  • Requests to provide banking information in order to ensure that the IRS can direct deposit an economic impact payment check.
  • Requests for any information from retirees in order to allow them to receive their economic impact payment.
  • Requests that refer to the economic impact payment as a “stimulus check” or “stimulus payment.”
  • Request for the economic impact payment to be signed over to somebody.
  • Request for verification of any personal or banking information in order to speed up the arrival of an economic impact payment.
  • Offers that claim to speed up economic impact payments.
  • Physical checks for an odd amount with instruction to call a number and verify information in order to cash it.

If you suspect that you may have received a fraudulent communication from somebody imitating the IRS, please reach out to phishing@irs.gov. You can also report suspected scams at irs.gov.

For more details, click here to read the IRS release in full.

CARES Act FAQ: Recovery Rebate

On March 27th, President Trump enacted the Coronavirus Aid, Relief, and Economic Security (CARES) Act. The historic $2.2 trillion stimulus bill includes an estimated $300 billion in direct payments to eligible American taxpayers.

Below, we address some of the common questions regarding this particular initiative. If you cannot find the answer to your question, please do not hesitate to reach out to your Slattery & Holman P.C. advisor for further assistance.

Who is eligible for the recovery rebate?

To receive any portion of the recover rebate, you must fit all of the following three criteria:

  1. Be either a U.S. resident or citizen,
  2. Not be the dependent of another taxpayer, and
  3. Have a work-eligible Social Security Number.

Additionally, there is an income limit set for receiving the rebate:

  • Single-filing taxpayers whose adjusted gross income (AGI) is under $75,000 are eligible to receive the whole amount; those whose AGI falls within $75,000 – $99,000 are eligible to receive a reduced rebate.
  • For married filing jointly, those with AGI under $150,00 are eligible to receive the whole amount and those in the $150,000 – $198,000 range are eligible to receive a reduced amount.
  • For those filing as head of household, the max AGI to be eligible to receive the full amount is $112,500 and the range for a partial rebate is $112,500 to $146,500.

How much is the recovery rebate?

The amount of your recovery rebate depends upon two factors: your adjusted gross income and how many children under the age of 17 you have. Taxpayers who qualify for the entire amount are eligible to receive $1,200 ($2,400 married filing jointly) plus $500 per child under 17. For the purposes of the recovery rebate, any child qualifies who is a qualifying child for the Child Tax Credit.

For taxpayers who earn above the $75,000/$150,000/$112,500 thresholds, the amount of the recovery rebate is reduced incrementally. For every $100 that the taxpayer’s AGI exceeds the phase-out threshold, their rebate is reduced by $5.  In general, the point of total phase-out is $99,000 for single filers, $198,000 for married filing jointly, and $146,500 for heads of household. For taxpayers with children, the point of total payment phase-out shifts. For example, married couples with two children who have an AGI greater than $150,000 but less than $218,00 would receive a portion of the recovery rebate.

What do I have to do in order to receive the rebate for which I am eligible?

For most eligible recipients, no action needs to be taken. The IRS will use the information from taxpayers’ 2019 tax returns (if filed) or their 2018 return to determine eligibility.

How will I receive the payment?

For those who filed 2019 or 2018 tax returns online, the IRS will direct deposit the payment into the same banking account reflected in the return field.

What if the IRS doesn’t have my direct deposit information?

The Treasury Department is working to develop a web-based portal to allow individuals to provide banking information to the IRS. The back-up plan is for individuals to receive payments via checks in the mail.

What if I didn’t file a tax return for either 2018 or 2019?

The best way to ensure that you receive the recovery rebate, if you are eligible, is to go ahead and file a 2019 tax return. Additionally, you can watch the IRS website for further instruction. The CARES Act includes a mandate to the IRS to engage in a public campaign to alert taxpayers of their eligibility and offer instructions on how to receive the rebate if they have not filed tax returns for 2018 or 2019.

The CARES Act also instructs the IRS to use additional tools to locate and provide rebates to eligible individuals who normally do not file a tax return due to their low income (e.g., seniors whose only income is from Social Security and veterans whose only income is a veterans’ disability payment). The IRS can base a rebate on Form SSA-1099, Social Security Benefit Statement or Form RRB-1099. That said, individuals in this situation are encouraged to go ahead and file a 2019 return in order to receive their rebate more quickly.

Other individuals with little income and those on means-tested federal benefits (such as SSI) are also eligible for the rebate—even those with $0 of income. However, they must not be the dependent of another taxpayer and they must have a work-eligible social security number.

What if my 2019 income was above the threshold but I make significantly less in 2020?

The recovery rebate is structured as an advance on a tax credit that eligible taxpayers may claim on their 2020 tax return. As such, if your income in 2020 is lower than in 2019, you will earn any additional credit for which you are eligible when you file your 2020 tax return.

Will my rebate be reduced because I have past due debt (federal or state, including student loan payments) and/or owe back taxes?

No, those situations will not cause a reduction of your rebate. The CARES Act waives nearly all administrative offsets that would ordinarily reduce tax refunds. There is one administrative offset that will still be enforced—the offset for those who have past due child support payments that the states have reported to the Treasury Department.

Here are a couple scenarios to further illustrate how the recovery rebate works:

Scenario 1: Jane Doe, who files as an individual, had 2018 AGI of $63,500 (she has not yet filed her 2019 tax return so the IRS will look at her 2018 return). In this scenario, she is entitled to receive the full $1,200 check, regardless of her 2019 tax liability.

Scenario 2: John and Sally Smith, who file as a married couple with 2 children under the age of 17, had 2019 AGI of $125,000.  In this scenario, they are entitled to receive a check for $3,400 as part of the individual stimulus payments.

CARES FAQ: Paycheck Protection Program & Economic Injury Disaster Loan

To Our Clients and Friends,

On March 27th, President Trump enacted the Coronavirus Aid, Relief, and Economic Security (CARES) Act. The historic $2.2 trillion stimulus bill includes $10 billion in funding to provide emergency grants to small businesses and nonprofits that apply for economic injury disaster loans.

Below, we address some of the common questions regarding this particular initiative. If you cannot find the answer to your question, please do not hesitate to reach out to your Slattery & Holman P.C. advisor for further assistance.

Emergency Economic Injury Grants

Who is eligible for an emergency economic injury grant?

Emergency economic injury grants are available to businesses and non-profits that apply for a Small Business Administration (SBA) economic injury disaster loan (EIDL). Typically, the timeline for EIDL approval and disbursement takes 3-4 weeks. That’s where the emergency economic injury grant comes in.

The goal of the emergency economic injury grant program is to provide a rapid funds advance within three days of the EIDL application. EIDL applicants simply need to request the emergency grant when they apply. The SBA will provide the grant within three days of receiving the EIDL application. Even if your application for the EIDL loan is denied, you do not have to repay the $10,000 emergency economic injury grant. That said, when you apply for the EIDL and request an emergency economic injury grant, you will be required to certify—under penalty of perjury—that you are eligible to receive an EIDL.

Please note: applicants must have been in operation on January 31, 2020 to receive the grant.

What can I use the emergency economic injury grant money for?

The grant can be used to provide paid sick leave to employees, maintain payroll, meet increased production costs due to supply chain disruptions, and/or pay business obligations (debts, rent, mortgage payments).

How do I apply for an emergency economic injury grant?

When you apply for an EIDL, you will have the opportunity to request the emergency grant at the same time. To apply for an EIDL, click here to visit the SBA website.

What if I apply for other SBA loan programs, like the Paycheck Protection Program?

You may apply for an EIDL, the emergency grant, and the Paycheck Protection Program (PPP). If you receive a loan through the PPP, the amount that is forgiven will be decreased by the $10,000 grant.

Paycheck Protection Program
What is the Paycheck Protection Program?
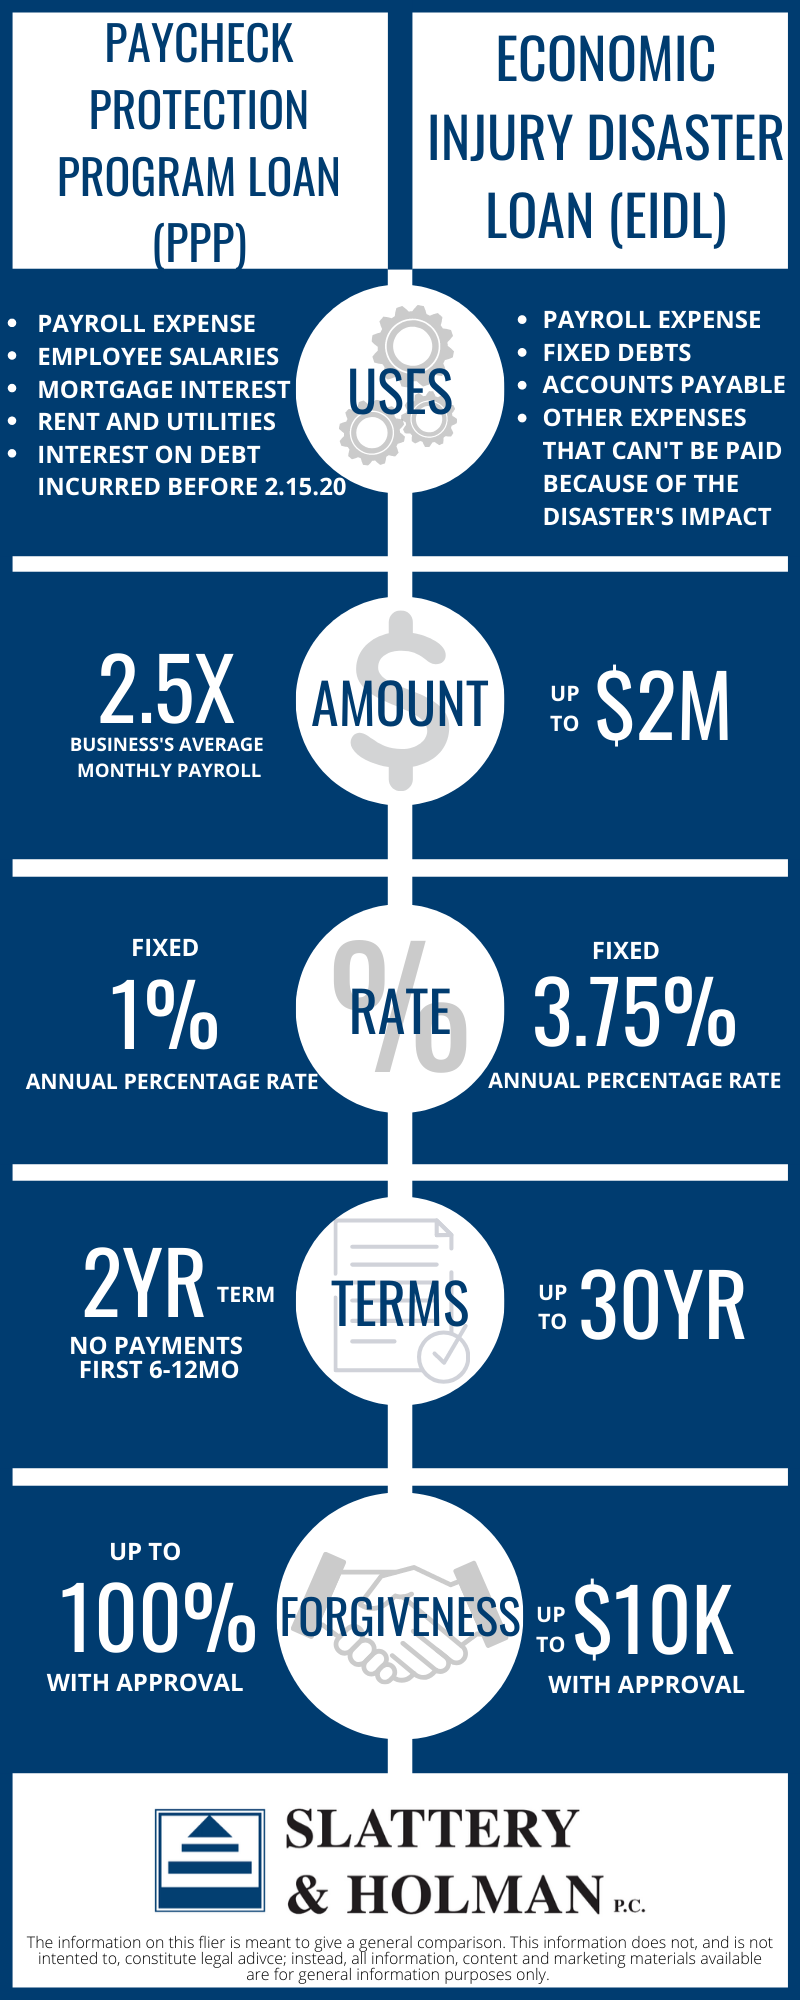
The CARES Act designates $349 billion for general business loans to be distributed under section 7(a) of the Small Business Act during a designated “covered period,” February 15 through June 30, 2020. Borrowers can qualify for up to $10 million in 100% federal government guaranteed covered loans. Under the CARES act, the portion of these loans that is used for allowable purposes will be forgiven.
Who qualifies for the program?
Firstly, businesses and other entities seeking PPP loans must have been in operation on February 15, 2020. Eligible recipients include:
  • Small businesses (fewer than 500 employees)
  • Sole proprietors, independent contractors, and eligible self-employed individuals (see below for more details)
  • IRC Section 501(c)(3) nonprofits
  • IRC Section 501(c)(19) veterans’ organizations
  • Tribal businesses under Section 31(b)(2)(C) of the Small Business Act (see below for more details)

For the purposes of the PPP, sole proprietors, independent contractors, and eligible self-employed individuals are those that are entitled to receive paid leave per the Emergency Paid Sick Leave Act. When applying, these individuals must submit documentation that establishes their eligibility (payroll tax filings, 1099s, and income/expense details for sole proprietorships). Tribal businesses that qualify are those with 500 or fewer employees (includes full-time, part-time, and other) or those that are the size standard established by the SBA for the industry in which they operate.

Eligible businesses can be precluded from receiving loans through the PPP by certain business affiliations. If the business is affiliated with a larger business (greater than 500 employees), they may be disqualified from participating in the PPP. An affiliation exists in two cases:

  1. One business controls another (or has the power to control it)
  2. A third party controls multiple businesses (or has the power to control them)
Additionally, the PPP expands eligibility to certain businesses with multiple locations, provided that each location has fewer than 500 employees. These eligible businesses have a North American Industry Classification System (NAICS) code that begins with 72 (accommodation and food services sector). The CARES Act waives affiliation rules for these businesses.
How much are the loans under the PPP?
The maximum loan amount is $10 million, though not every applicant is eligible for that amount. There are three methods by which an entity’s loan amount can be calculated:
  1. For entities in business from February 15, 2019 – June 30, 2019: Calculate your average total monthly payments for payroll during the period and multiply it by 2.5.
  2. For entities that were not in business from February 15, 2019 – June 30, 2019: Calculate your average total monthly payments for payroll between January 1, 2020 and February 29, 2020 and multiply it by 2.5.
  3. For entities that took out an Economic Injury Disaster Loan (EIDL) between February 15, 2020 and June 30, 2020: You can refinance your loan into a PPP loan. Add the outstanding loan amount to the payroll sum.

How can the loan money be used?

Allowable uses of the PPP loans include:

  • Salaries, wages, commissions, or similar compensations (up to $100,000 per year per employee, prorated)
  • Cash tips or equivalent
  • Employee leave, including parental, family, medical, or sick (excluding family or sick leave under the Families First coronavirus Response Act)
  • Allowances for dismissal or separation
  • Group healthcare benefits, including insurance premiums, excluding >2% shareholders
  • Retirement benefits
  • State or local taxes on employee compensation (not including the employer’s share of FICA payroll taxes, railroad retirement act taxes, or other required U.S. income tax withholding)
  • Continuation of group healthcare benefits during employee leave and insurance premiums
  • Mortgage interest, rent, utility payments (including phone and internet), and any other debt obligations incurred prior to February 15, 2020

Additionally, sole proprietors and independent contractors may use the loan money to cover compensation and income of up to $100,000 per year (prorated).

What if I use the money for a non-allowable purpose?

Loan money used for any of the allowable purposes listed above will be forgiven; loan money used for non-allowable purposes must be repaid. Any balance remaining, after the amount used on allowable purposes is forgiven, will continue to be a fully guaranteed loan for up to ten years from the date of application.

What fees are associated with getting a PPP loan?

All service fees, prepayment fees, and borrower guarantees are waived for PPP loans.

What sort of collateral or personal guarantees are required?

Loans covered under the PPP require neither collateral nor personal guarantees, if the money is used for allowable purposes.

What is the interest rate on the loans?

The maximum interest rate is 1%.

What if I can obtain credit elsewhere?

While normally SBA loans only go to borrowers who cannot obtain credit elsewhere, for PPP loans, this requirement is waived.

How do I apply for the program?

The SBA and the Department of Treasury have approved thousands of institutions to be authorized lenders for the PPP. You can contact any local banking institution to find out if they are an approved lender, or use the Lender Match, an online tool from the SBA. Additionally, you can reach out to an SBA development center for local assistance in finding a lender.

CARES Act FAQ: Emergency Economic Injury Grants

On March 27th, President Trump enacted the Coronavirus Aid, Relief, and Economic Security (CARES) Act. The historic $2.2 trillion stimulus bill includes $10 billion in funding to provide emergency grants to small businesses and nonprofits that apply for economic injury disaster loans.

Below, we address some of the common questions regarding this particular initiative. If you cannot find the answer to your question, please do not hesitate to reach out to your Slattery & Holman P.C. accounting advisor for further assistance.

Who is eligible for an emergency economic injury grant?

Emergency economic injury grants are available to businesses and non-profits that apply for a Small Business Administration (SBA) economic injury disaster loan (EIDL). Typically, the timeline for EIDL approval and disbursement takes 3-4 weeks. That’s where the emergency economic injury grant comes in.

The goal of the emergency economic injury grant program is to provide a rapid funds advance within three days of the EIDL application. EIDL applicants simply need to request the emergency grant when they apply. The SBA will provide the grant within three days of receiving the EIDL application. Even if your application for the EIDL loan is denied, you do not have to repay the $10,000 emergency economic injury grant. That said, when you apply for the EIDL and request an emergency economic injury grant, you will be required to certify—under penalty of perjury—that you are eligible to receive an EIDL.

Please note: applicants must have been in operation on January 31, 2020 to receive the grant.

What can I use the emergency economic injury grant money for?

The grant can be used to provide paid sick leave to employees, maintain payroll, meet increased production costs due to supply chain disruptions, and/or pay business obligations (debts, rent, mortgage payments).

How do I apply for an emergency economic injury grant?

When you apply for an EIDL, you will have the opportunity to request the emergency grant at the same time. To apply for an EIDL, click here to visit the SBA website.

What if I apply for other SBA loan programs, like the Paycheck Protection Program?

You may apply for an EIDL, the emergency grant, and the Paycheck Protection Program (PPP). If you receive a loan through the PPP, the amount that is forgiven will be decreased by the $10,000 grant.

CARES Act FAQ: Retirement Plan Withdrawals

On March 27th, President Trump enacted the Coronavirus Aid, Relief, and Economic Security (CARES) Act. The historic $2.2 trillion stimulus bill includes an allowance for penalty-free early withdrawals from retirement accounts.

Below, we address some of the common questions regarding this particular initiative. If you cannot find the answer to your question, please do not hesitate to reach out to your Slattery & Holman P.C. accounting advisor for further assistance.

What changes did the CARES Act make to retirement withdrawals?

For 2020, eligible plan participants can now receive coronavirus-related distributions from their retirement plans (401(k)-type defined contribution plans or individual retirement accounts (IRAs)).

Am I eligible to make a withdrawal from my retirement account?

To be eligible, you must fit at least one of the following criteria:

  1. You or your spouse or dependent has been diagnosed with COVID-19, or
  2. You have suffered adverse financial consequences due to COVID-19 (e.g., suffering loss of business, unable to work due to childcare, required to quarantine, put on furlough, etc.)

Plan participants will simply self-certify that they meet the conditions for a coronavirus-related distribution.

How much can I withdraw from my retirement account?

Eligible individuals can take out up to $100,000.

If I make early withdrawals, do I have to pay a penalty?

No, if you make an eligible withdrawal you are exempt from the 10 percent early withdrawal penalty. Additionally, the 10 percent penalty waiver applies retroactively to withdrawals beginning January 1, 2020.

When do I pay taxes on the money I withdraw?

Income taxes are still owed on withdrawn amounts. The CARES Act allows for tax payments to be spread over a three-year period.

Is there a way to re-invest the money that I take out?

Yes, individuals who make coronavirus-related withdrawals may replace the money within three years, regardless of the annual contribution level of their plan. Additionally, they may also be able to recover the federal and state income taxes that they paid.

 I already have one or more loans on my 401(k), can I still take a coronavirus-related distribution?

This depends on the particular rules of your plan—consult your plan sponsor.

Updated State of Affairs, Tax and Compliance Changes

To Our Clients,

It is our hope that you are healthy and safe as the Coronavirus continues to impact our lives in extraordinary ways.  We remain alert to news about the rapidly evolving state of affairs and any tax and compliance changes that affect you, your families and your businesses.  We are here to provide answers and advice to assist you in navigating this situation as it unfolds.

Key changes to tax filing and payment deadlines:

  • Both the federal and Indiana governments have extended filing and payment deadlines from April 15 to July 15.
  • All individual and business taxpayers have the additional 90 days to file income tax returns and make tax payments without interest or penalties.
  • First quarter federal and Indiana estimated tax payment deadlines for both individuals and corporations have also been extended to July 15.
  • Additionally, contributions to traditional, SEP and Roth IRAs, as well as HSAs, are also now due July 15.
  • Answers to frequently asked questions regarding this relief can be found here: https://www.irs.gov/newsroom/filing-and-payment-deadlines-questions-and-answers.
  • Other states are responding with similar filing and payment deadline changes and these vary by state. We will keep you apprised of those updates as they apply to your specific situation.

 Regardless of a change in deadline, our firm will continue to operate with the goal of completing tax filings without relying on extensions in an effort to provide you with information you may need for cash flow planning and financing.

Legislation / CARES Act 

  • A $2.2 trillion Coronavirus relief package. This is the largest rescue package in American history.
  • Key provisions include individual stimulus checks, unemployment insurance, employee retention credit and job loss prevention loans, emergency lending for industries, emergency aid to state, local and tribal governments and the American medical system, and several business and individual tax provisions.

We will continue to communicate the particulars of the CARES Act and what it may mean for you.  With the recent passing, the implementation details and specifics are still being interpreted.

Our website will address other issues and changes related to the COVID-19 pandemic.  Please visit our website over the coming days at www.slatterycpa.com and click the Coronavirus link where we will post helpful articles and links to keep you informed.

We have essentially transitioned to a remote work environment in order to do our part to reduce the risk of exposure.  We respectfully ask you take advantage of our electronic capabilities such as secure portal and email for document transfer, and SafeSend, our new delivery service for reviewing and signing tax returns.  Should you need to coordinate physical delivery of documentation that cannot be provided electronically, please contact us to make other arrangements since office visits are no longer practical at this time.  We are still readily available to you via phone and email as well as other electronic platforms.

Continue to reach out to us with any questions or concerns as we get through this together.

Warm regards and stay safe,

Slattery & Holman, P.C.