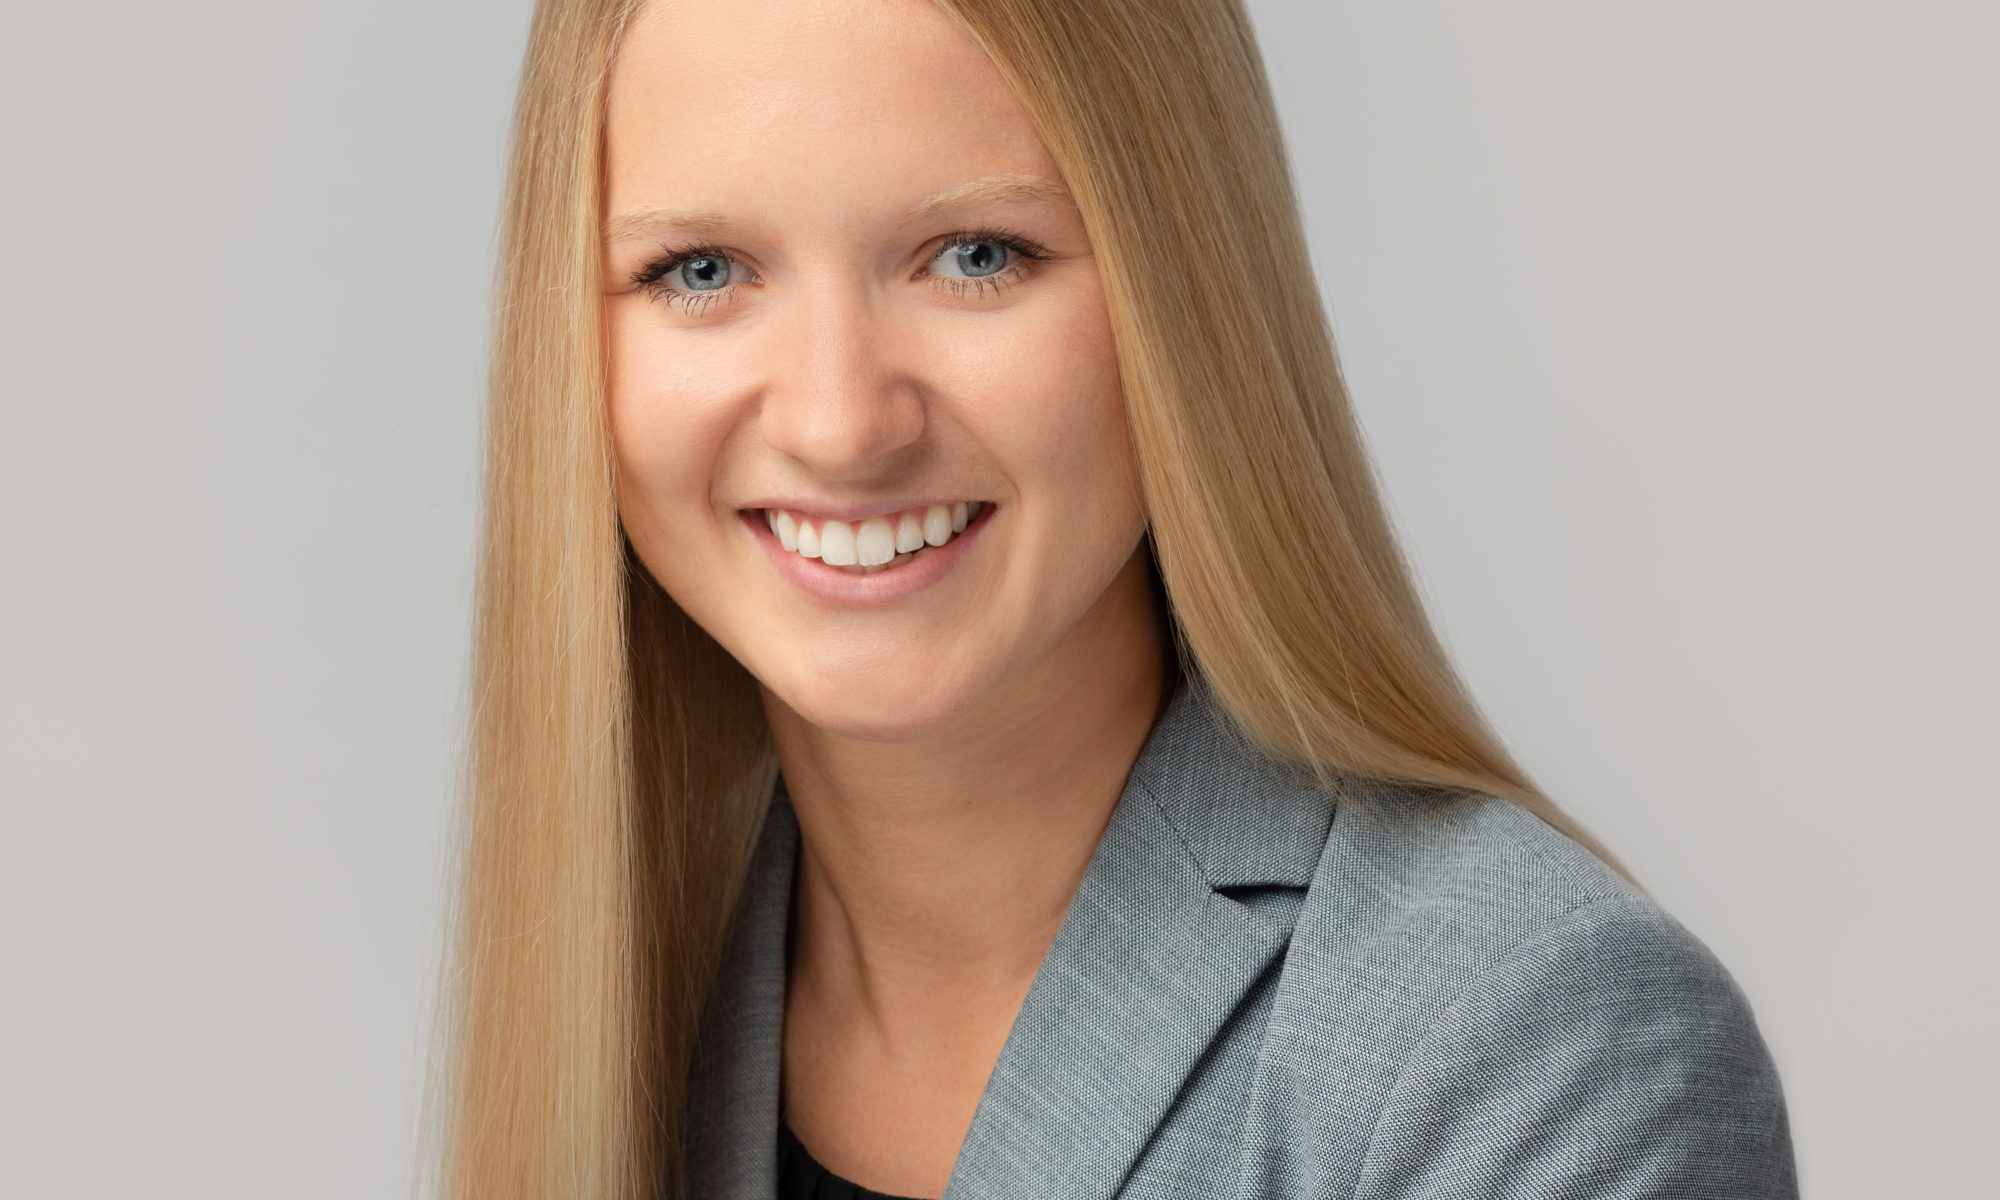
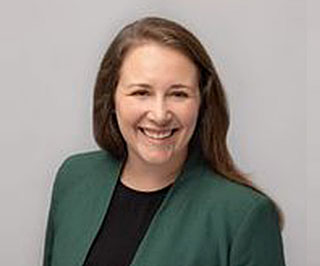
Employee Spotlight – Erica Stout

Erica L. Stout

What year did you join Slattery & Holman?
July 2021

Tell us a little about where you attended college and the degree(s) you earned? Any special accomplishments.
IU Bloomington B.S. in Accounting and Finance

What is your favorite thing about living in Indiana?
The Indy airport and fall in Bloomington.

Tell me a little about your family.
My husband, Nick, is also a CPA.  We have one son, John, who keeps us very busy.

If you didn’t have to sleep, what would you do with the extra time
Travel to either ski, see musicals, or visit art museums.

What is a new skill that you would like to master?
Speak a different language fluently.

What do you wish you knew more about?
All history, especially my family’s ancestry.

What’s the farthest you’ve ever been from home?
Italy

What is the most impressive thing you know how to do?
Get a toddler to sleep.

What was the best compliment you’ve ever received?
“You are always able to smile and put on a brave face.”

What silly accomplishment are you most proud of?
Roasting coffee beans.  It is way harder than it sounds.

What is your favorite smell?
Coffee

If you could have any super power, what would it be?
Teleportation! It would be amazing to just appear in a different city for dinner with family/friends who are far away.

Business Success Stories – The Explosive Growth of Zoom

Video conferencing in and of itself is certainly nothing new. It’s been around in some form or another for decades — businesses used it for remote meetings in the 1990s, and personal users have been “Skyping” with friends and family since high-speed Internet connections found their way into homes. Certain organizations have become virtually synonymous with the trend in much the same way that “Google it” has become shorthand for “search for something online.” Zoom Video Communications is one such company.

Originally launched in 2013 by a former Cisco engineer and executive named Eric Yuan, Zoom has enjoyed an almost unprecedented level of growth over the last two years, thanks largely to the ongoing COVID-19 pandemic. In March 2020, as the Coronavirus began to make its way around the world, people were sent to work from home indefinitely. Of course, they still needed a way to communicate and collaborate with one another. They suddenly had to figure out how to be just as productive at home as they could be in the office. For many, Zoom became that solution.

Charting the Rise of Zoom

It’s clear that COVID-19 has contributed enormously to Zoom’s current success. In January 2020, for example, it was estimated that the service saw approximately 56,000 daily downloads. By February, that number had already climbed to 1.7 million. Just a month later, when worldwide lockdowns and other social distancing restrictions began, it had risen again to 2.13 million — a trend that shows no signs of slowing down anytime soon.

Likewise, the platform has also seen a dramatic surge in the number of people participating in meetings every day. After all, Zoom is a free download from both the service’s website and various app stores. Downloads don’t amount to much if people aren’t actively using the software, but thankfully for Zoom, they are. In December 2019, there were approximately 10 million daily meeting participants according to the same research mentioned above. In March 2020, that number had climbed to 200 million. Another month later and it hit more than 300 million.

The idea for Zoom was born from Eric Yuan, an immigrant from China who first arrived in the United States in the 1990s. Even back then, he was passionate about finding a way to make video calls not only easy, but portable — and this was before the advent of the smartphone.

His career began at WebEx, where he worked as an engineer. After WebEx was acquired by Cisco a decade later, he became that company’s Corporate Vice President of Engineering. He experienced a tremendous amount of success during that time, but he had visions of something bigger.

While he was at Cisco, Yuan listened carefully to customers express various complaints about how WebEx operated. They were constantly dealing with unreliable connections, a disconnect between the audio and video, etc. They even found the installation process frustrating, particularly in IT departments that were working with a large number of users.

Customers wanted something faster, more reliable, more efficient and more straightforward. Yuan was more than happy to oblige.

In 2011, he left Cisco and began to work on the solution that would become Zoom. It officially launched in January 2013 and was a major hit right out of the gate. Not only did Zoom hit one million active participants just a few months later in May, but Yuan was also able to secure funding of $10 million to continue his work.

Even before the pandemic, Zoom found ways to differentiate itself from many other competitors in the marketplace. For starters, Yuan prioritized very low data usage, meaning that calls would still function on slower Internet connections and mobile devices. Not only that, but Zoom was cloud-based, virtually eliminating the installation process and making it available on any device or platform — no exceptions. The Pro package cost just $9.99 per month at its launch, which was far cheaper than almost anything out there. In addition, Zoom was offered to K-12 schools free of charge in many of the countries it had entered.

The aforementioned features combined to form the perfect storm. Zoom slowly began to increase its market share, then the COVID-19 pandemic acted as an accelerant that solidified what many in the industry already knew: video conferencing was here to stay, and Zoom was now a frontrunner.

We hope to inspire business owners by sharing success stories like Zoom’s. If you need any assistance with your start-up or scaling your business, feel free to give us a call.

Fall Tax Planning May Be Wise

Taxes are like vehicles in that they need a periodic check-up to make sure they are performing as expected, and if ignored, could cost you money.

The following is a list of potentially beneficial tax strategies. Every taxpayer’s situation is unique, and not all of the strategies suggested here will apply to you. However, opportunities for tax planning are available for all income levels and a variety of tax circumstances.

Maximize Education Tax Credits – If you qualify for either the American Opportunity Tax Credit (AOTC) or Lifetime Learning Credit (LLC), check to see how much you have already paid for qualified tuition and related expenses during the year. If you have not met the maximum amount allowed for computing the credits, you can prepay 2022 tuition if it is for an academic period beginning in the first three months of 2022 and use the expense for the 2021 credit.

Convert Traditional IRAs to Roth IRAs – If your income is unusually low this year, or even negative, you may wish to consider converting your traditional IRA to a Roth IRA. A Roth IRA allows earnings to grow tax-free, and distributions are tax-free at retirement. Lower income results in a lower tax rate, which provides you an opportunity to convert to a Roth IRA while minimizing taxes paid.

Don’t Forget Your 2021 Minimum Required Distributions – If you are 72 or older, you must take required minimum distributions (RMDs) from your IRA, 401(k) plan and other employer-sponsored retirement plans (but if you are still working, distributions from your current employer’s plan can be postponed in some circumstances). Failure to take a required withdrawal can result in a 50% penalty of the amount of the RMD not withdrawn. If you turned 72 in 2021, you could delay the first RMD to the first quarter of 2022, but if you do, you will have to take a double distribution in 2022 (one for 2021 and 2022). One should carefully consider the tax impact of a double distribution in 2022 versus a distribution in both this year and next.

Bunching Deductions – If your tax deductions normally fall short of needing to itemize because the standard deduction you are allowed is greater, or if itemizing is only marginally beneficial, you may benefit from adopting the “bunching” strategy. To be more proactive, you can time the payments of tax-deductible items to maximize your itemized deductions in one year and take the standard deduction in the next.

Take Advantage of the Zero Capital Gains Rate – There is a zero long-term capital gains rate for those with taxable income below the 15% capital gains tax threshold. This may allow you to sell some appreciated securities that you have owned for over a year and pay very little to no tax on the gain.

Defer Deductions – When itemizing deductions, you may only claim deductions you paid during the tax year (the calendar year for most folks). If your projected taxable income is negative and you plan to itemize your deductions, consider putting off some of your year-end deductible payments until after the first of the year to preserve the deductions for next year. Such payments might include house of worship tithing, year-end charitable giving, tax payments (but not those incurring late payment penalties), estimated state income tax payments, medical expenses, etc.

Increase IRA Distributions – Depending on your projected taxable income, you might consider taking an IRA distribution to add income for the year. For instance, if your projected taxable income is negative, you can take a withdrawal of up to the negative amount without incurring any income tax. Even if your projected taxable income is not negative and your normal taxable income would put you in the 24% tax bracket or higher, you might want to take out just enough to be taxed at the 10% or 12% rate. Since those are retirement dollars, consider moving them into a regular financial account set aside for your retirement. Also be aware that distributions before age 59½ are subject to a 10% early withdrawal penalty.

Defer Capital Gains by Investing in an Opportunity Zone Fund – A unique tax benefit is the ability to defer any capital gain into a qualified opportunity fund (QOF). QOFs are funds that invest in areas in need of development. If you have a capital gain from selling property to an unrelated party, you may elect to defer that gain by investing it into a QOF within 180 days of the sale or exchange. The gain won’t be recognized (i.e., you won’t be taxed on the gain) until you file for the tax year in which the QOF is sold, or 2026, whichever comes first. You can get up to 10% of the deferred gain forgiven by holding the investment for the required time period, and you will pay no tax on any additional gain if the investment is held for 10 years.

Sell Loser Stocks – Although the stock market has been performing well recently, you still may have stocks that have declined in value. If you sell them before the end of the year, you can use any losses to offset other gains for the year or produce a deductible loss. The net capital loss deductible on a tax return is limited to $3,000 ($1,500 if filing married separate) for the year, but any excess loss carries over to future years. You can repurchase stock in the same company from which you sold shares at a loss after 30 days have passed and avoid the wash sale rules.

Don’t Waste the 2021 Annual Gift Tax Exemption – To limit your estate’s exposure to inheritance taxes, you can give $15,000 each to an unlimited number of individuals in 2021, but you can’t carry over unused exclusions from one year to the next. Taxpayers and their spouses can use their gift tax exemptions together to give up to $30,000 per beneficiary. For example, if you are married and have four children and four grandchildren, you can remove $240,000 from your estate tax-free this year. The transfers may also save family income taxes when income-earning property is given to family members who are in the lower income tax brackets and are not subject to the kiddie tax.

Not Needing to File May Be an Opportunity – If your income and tax situation is such that you don’t need to file for 2021, don’t overlook the opportunity to bring in some additional income (to the extent it will be tax-free). For instance, if you have appreciated stock that you can sell without incurring any tax, consider selling it. Another option is to take a Roth IRA distribution if you are 59½ or older, or if you are younger and qualify for an exception to the early withdrawal penalty.

Utilize IRA-to-Charity Transfers – If you are 70½ or over, you can request that your IRA trustee directly transfer funds from your IRA to a charity. Although not deductible as an itemized charitable deduction, the distribution is not taxable. If you are 72 or over when a direct transfer is made, the distribution can count towards your required minimum distribution for the year. This also reduces your AGI, which in some circumstances can reduce the amount of taxable Social Security income. There is no minimum charitable distribution, but the maximum amount per individual is limited to $100,000 per year. There are some complications if you are 72 or older, have earned income and make a contribution to the IRA. Check with our office for the details.

Maximize Tax-Deductible Medical Expenses – If you have outstanding medical or dental bills, paying the balance before year-end may be beneficial, but only if you already meet the 7.5% of the AGI floor for deducting medical expenses, or if adding the payments would put you over the 7.5% threshold and you are itemizing your deductions. You can even use a credit card to pay the expenses, but you would only want to do so if the interest you would incur if you don’t pay off the card right away is less than the tax savings.

Make Business Purchases – You can reduce taxable income if you make last-minute business purchases, such as office equipment, tools, machinery and vehicles, and write them off using 100% bonus depreciation or Sec. 179 expensing, provided you place the item(s) into business service by the end of the year. However, you must consider the impact that expensing the items will have on your taxable income and the Sec. 199A 20% pass-through deduction. It may be appropriate to contact us in advance of any last-minute business acquisitions.

Divorced or Separated During the Year – A divorce or separation can have a significant impact on a couple’s tax filings. Issues to be considered include whether to file joint or separate returns, who will claim the children, whether to take the standard deduction or itemize, how income and tax prepayments are to be allocated, etc.

Increased Charitable Giving Opportunities – 2021 is the final year that the normal 60% of AGI limit on cash contributions has been increased to 100%, providing an opportunity for those with the means and desire to increase their normal charitable contributions and deduct them as an itemized deduction. The normal 5-year carryover applies to any excess over 100% of AGI.

Those who don’t itemize (currently about 90% of income tax return filers), are allowed to claim a deduction of up to $300 ($600 on a joint return) for cash charitable contributions made in 2021. Normally, only itemizers can deduct their charitable contributions.

Take Advantage of Energy Credits – Two of the major green credits are the solar tax credit and electric vehicle credit. The solar credit for 2021 is 26% of the cost of the installed solar system, but the system must be complete and functional before year’s end to claim the credit in 2021. The credit is not refundable, and any excess has a limited carryover. The credit for electric vehicles must be determined using the IRS website since the credit begins to phase out once 200,000 of the vehicle type by manufacturer have been sold.

Other Considerations – If you have obtained medical insurance through the government’s marketplace, employing some of the strategies mentioned could impact the amount of your allowable premium tax credit.

Residents of states that have an income tax will also need to consider the impact of some of these strategies on their state return.

If you would like to schedule a tax planning appointment to determine strategies that best fit your circumstances, please give our office a call.
Key Tax Provisions Included in New Infrastructure Bill

On November 5, the House voted to pass the Infrastructure Investment and Jobs Act (IIJA), which had previously passed in the Senate. The bill now heads to the White House, where President Biden is expected to sign it into law.
Though the main focus of the new legislation is on allocating tax dollars for infrastructure investment throughout the nation, the IIJA also contains a number of tax provisions. A recent article from the Journal of Accountancy offers a helpful overview of the tax changes, which include the following:
 
  • An early end to the employee retention credit (ERC)
  • New reporting requirements for brokers working with cryptoassets
  • Modification of automatic extensions for taxpayers affected by federally declared disasters and the language defining a disaster area
  • Extensions of some highway-related taxes
  • Extensions and modifications of some superfund excise taxes
  • Allowance of private activity bonds for broadband projects and carbon dioxide capture facilities that meet certain qualifications

Tax Issues Related to Renting Your Vacation Home

Do you own a second home at the beach, in the mountains or another getaway location? Or are you thinking about buying one? If so, then you may have thought about the possibility of renting it out. Doing so can offset some of the expenses related to the property, and you may even reap a tax benefit at the same time. Whichever route you choose to go, knowing the applicable tax rules regarding designated second home can help you get the maximum financial benefit out of your asset and keep you from making tax filing errors.

If You Don’t Rent Your Property

Depending upon your individual tax situation, a designated second home’s acquisition mortgage interest may be eligible as an itemized deduction. However, there is a limit on the amount of acquisition debt for a taxpayer’s main residence and one additional home for which the interest is deductible. For a primary residence and second home acquired on or before December 15, 2017, that limit is $1,000,000 ($500,000 if married filing separately). After December 15, 2017, the limit is reduced to $750,000 (except that debt incurred prior to that date still falls under the $1,000,000 limit).

Real property taxes on your main and any number of additional homes are also deductible if you itemize deductions when figuring your regular tax, but not for the alternative minimum tax (AMT). However, even though itemized taxes include property tax, state income tax and certain other taxes, the total amount allowed per year is limited to $10,000 ($5,000 if you are married filing separately), so the deduction for some of your taxes may be limited.

If You Rent Your Property

­The tax implications of renting out your designated second home are largely dependent upon the amount of time that it is rented out during the year. Your home will fall into one of these three categories:

  • Rented 14 days or fewer: When you rent out a dwelling unit that you use as a residence–whether it’s your main home or a second home–for a period that is 14 days or fewer during the year, you do not report the income and cannot deduct any rental-related expenses. However, you are still able to continue writing off eligible mortgage interest and real property taxes as itemized deductions.
  • Rented 15 days or more, and personal use does not exceed 14 days or more than 10% of rental days: In this scenario, the home’s use would be allocated into two separate activities: a second home and a rental home. For example, if the home is used 5% for personal use, then 5% of the total interest and taxes would be treated as home interest and taxes that can be taken as an itemized deduction. The other 95% of the interest and taxes would be rental expenses, combined with 95% of the insurance, utilities and allowable depreciation, and 100% of the direct rental expenses. The result can be a deductible tax loss, which would be combined with all other rental activities and limited to a $25,000 loss per year for taxpayers with modified adjusted gross incomes (MAGI) of $100,000 or less. This loss allowance is ratably phased out when MAGI is between $100,000 and $150,000. Therefore, if your income exceeds $150,000, the loss cannot be deducted. Instead, it is carried forward until the home is sold or there are gains from other passive activities that can be used to offset the loss.
  • Rented 15 days or more, and personal use exceeds 14 days or more than 10% of rental days: For those whose personal use of the home is more than 10% of the amount of time that it is rented (or more than 14 days, whichever is greater), no rental tax loss is allowed. Let’s assume that the personal use of the home is 20%. As for the remaining 80%, it is used as a rental. The rental income is first reduced by 80% of the taxes and interest. If after deducting the interest and taxes, there is still a profit, the direct rental expenses (such as the rental portion of the utilities, insurance and any other direct rental expenses) are deducted, but no more than will offset the remaining income. If there is still a profit, you can take a deduction for depreciation of the building, furnishings, etc., but it is again limited to the remaining profit. End result: No loss is allowed, but any remaining profit is taxable. The personal 20% of the interest and taxes is deducted as an itemized deduction, subject to the interest, taxes and AMT limitations discussed earlier.

If You Sell Your Vacation Home

Even if you use your vacation home to generate rental income, it is still considered to be a property for your personal use, and that means that once you sell it, you are subject to taxation on any gains you realize. By contrast, if the sale results in a loss, you are not permitted to deduct any losses–at least not in the examples we’ve provided above. In some cases, a loss on a property can be broken down between the personal use (nondeductible) and the business rental portion (deductible).

If You Sell Your Home

When you sell your primary home, you are able to take advantage of what is known as the home gain exclusion, but this is not true of designated second homes. The gain from the sale of a second home is taxable, but eligible for favorable capital gains tax rates in most cases. The only exception to this rule is when the taxpayer has occupied the second home as their primary residence for at least two of the five years immediately before the sale takes place. At no time during that two-year period can the home have been rented. When this is the case, and the taxpayer hasn’t applied the home gain exclusion on the sale of another property in the previous two years, the taxpayer is able to take the exclusion. Doing so would allow married homeowners to exclude up to $500,000 of the home’s gain from their income, and single homeowners to exclude up to $250,000, except for depreciation of the home that has previously been deducted.

Other Issues

There are certain situations involving designated second homes that are particularly complex, such as homes that are converted from an investment property to a primary residence, or those acquired by tax-deferred exchange. In these instances, it is essential that you consult with your tax advisor in order to ensure that all appropriate planning is done to provide you with the most benefit.

If you rent out your property and provide additional services such as maid service, or rent it out for short-term stays, the IRS may view that activity as a business operation rather than a rental. When this is the case, the tax ramifications are entirely different. Because of this and many other complicating factors and exceptions, we encourage you to contact our office to review the tax impact of your real estate transactions.

Employee Spotlight – Kaylan Hudson

Employee Spotlight – Kaylan Hudson

What year did you join Slattery & Holman?
2019

Tell us a little about where you attended college and the degree(s) you earned? Any special accomplishments.
Indiana University Kokomo, where I double-majored in Accounting & Business Management.  I’m the only child to graduate from college in my immediate family thus far.

What is your favorite thing about living in Indiana?
The change of seasons.

Tell us a little about your family.
I come from a blended family with a total of 5 kids (3 girls, 2 boys) ranging from age 16 – 30.  The majority of my immediate family resides in north-central Indiana.

If you didn’t have to sleep, what would you do with the extra time?
What wouldn’t I do?  Exercise and do yoga every day, meal prep better and cook every day, and spend more time with family & friends.

IRS Extends COVID-19 Relief Leave Donations

As part of the emergency disaster declaration made by President Trump on March 13, 2020, it became possible for employees to donate their unused paid sick, vacation or personal leave to qualified charities that provided COVID-19 relief in 2020.

The IRS recently extended leave donations through 2021. This is a great opportunity to provide sorely needed help in the ongoing COVID-19 pandemic without any cost to you. Check with your employer to see if they are participating and for more information. If your employer is unaware of this program, refer them to IRS Notice 2020-46 and 2021-42.

Here is how it works: if your employer is participating, you can relinquish any unused sick, vacation or personal leave for cash payments which your employer will donate to COVID-19 relief charitable organizations. The cash payment will not be treated as wages to you, and your employer can deduct the amount donated as a business expense. However, since the income isn’t taxable to you, you will not be allowed to claim the donation as a charitable deduction on your tax return. Even so, excluding income is often worth more as tax savings than a potential tax deduction, especially if you generally claim the standard deduction or are subject to AGI-based limitations.

This special relief applies to all donations made before January 1, 2022, giving individuals plenty of time to forgo their unused paid leave and have the cash value donated to a worthy cause.

If you have questions related to donating leave time for COVID-19 relief efforts, or other charitable contributions, please contact our office.

Entrepreneur Success Story: How Canva Reached a $15 Billion Evaluation and Made Its Young Founders Billionaires

Human beings are visual learners. They always have been, and they always will be.

A big part of this has to do with the way the human brain works. According to one recent study, when people hear information, they generally only remember about 10% of it. If that information is paired with relevant visuals, such as a video or static content like a photo or infographic, they remember an average of 65% of the information. In fact, it’s estimated that between 51% and 80% of all businesses in every industry will rely heavily on visual content in 2021–a trend that shows no signs of slowing down any time soon.

That, in essence, is what Canva is all about.

Canva is a graphic design platform which can be used to create visual content like social media graphics, presentations, posters and more. The app includes templates that make it easy to create the stunning content you need.

The platform itself is available for free, although it does offer paid subscriptions through its “Canva Pro” and “Canva for Enterprise” tiers that unlock additional features. Not only can users create content that immediately exists online, but they can also pay for physical products to be printed and shipped to customers, allowing brands of all types to make meaningful connections with their target audiences.

In April 2021, Canva reached a $15 billion valuation, simultaneously making its co-founders Melanie Perkins and Cliff Obrecht billionaires. This came less than a year after securing a $6 billion valuation in spite of the COVID-19 pandemic.

But what may seem like an overnight success was, for those co-founders, anything but. The development of Canva wasn’t easy, but it is an inspiration to entrepreneurs and businesses professionals everywhere.

Canva: The Story So Far

The idea that would go on to become Canva began in January 2012 in Perth, Australia. It was then that Perkins, Obrecht and a third co-founder, Cameron Adams, saw a market that was in desperate need of being filled.

The company began simply enough: They wanted to “make design accessible to all.” It didn’t matter what you needed those design services for–logos, business cards, presentations or something else entirely.

When Perkins and Obrecht were in college in Perth, the duo would earn side income by teaching other students various design programs. After determining that some of the platforms offered by companies like Microsoft and Adobe had too much of a learning curve, they thought there had to be a better way.

But when they couldn’t find it, they decided to create the “better way” themselves.

The duo–now a couple–started an online school yearbook design business that was then called Fusion Books. They immediately launched a website that let users collaborate and build their profile pages, articles and other content for those online school yearbooks. Perkins and Obrecht would then print the yearbooks, after which they would deliver them to schools across the country.

The business was a success, but the pair didn’t want to stop there. They wanted to go bigger, and they had ideas on how to do it.

In 2010, Perkins had an encounter with an investor from Silicon Valley who saw the potential in such an idea. That investor introduced her to a few contacts, at which point they began to develop their idea even further. With the help of a few technology advisors, and after the close of their first funding round, Canva was born.

One year after launching, Canva had more than 750,000 active users. Now focused on marketing materials, its revenue increased from an already impressive $6.8 million to an enormous $23.5 million during the 2016-2017 fiscal year alone. In 2018, the company had raised more than $40 million from various investment firms and was already valued at $1 billion.

The takeaway from Canva’s story is there is truly no idea too small (or too niche) to make an impact. Melanie Perkins and Cliff Obrecht were tired of spending time teaching complicated graphics programs to fellow students, so they decided to create a platform of their own to eliminate as much of the “hard work” as possible. That simple idea turned into something much larger than either of them could have imagined.

Employee Spotlight – Karen Keinsley

What year did you join Slattery & Holman?
2007

Tell me a little about where you attended college and the degree(s) you earned? Any special accomplishments.
I attended IU Southeast in New Albany, IN.  I majored in business with a concentration in accounting.

What is your favorite thing about living in Indiana?
The people.  Hoosier hospitality really does make a difference.

Tell me a little about your family.
I have been married for 40 years to a wonderful man who is the most patient person I know.  We have two grown sons who are married and have blessed us with 5+ grandchildren.  Number 6 is due in November 2021.  We live on 13 acres in Madison County.  I grew up on a farm, so I enjoy being outdoors and everything Mother Nature has to offer.

If you didn’t have to sleep, what would you do with the extra time?
I don’t sleep much, so there’s not much extra time.

What is a new skill that you would like to master?
Sign Language

What’s the farthest you’ve ever been from home?
3,644 miles – Fairbanks, Alaska

What question would you most like to know the answer to?
What do I want to be when I grow up?

What is the most impressive thing you know how to do?
I know how to ballroom dance.

What was the best compliment you’ve ever received?
A friend told me I was the nicest person they had ever known.

What is your favorite smell?
Lilacs

If you had a clock that would countdown to any one event of your choosing, what event would you want it to countdown to?
My last day on the earth.  Every day is precious, so I don’t want to waste them.

What’s the most unusual thing you’ve ever eaten?
Groundhog or raccoon

What was your first job?
Hostess at IHOP

If you could have any super power, what would it be?The power to help others know they are loved and that you don’t have to follow the crowd. It’s ok to just be yourself.